RBI Shocks With First Rate Hike in Four Years
India's RBI raised the repo rate 25 bps to 5.50% today in a unanimous vote — reversing 125 bps of cuts as Brent crude tops $100 and CPI risks mount.
Key Points
- The RBI raised its repo rate 25 bps to 5.50% today in a unanimous 6-0 vote, reversing course after cutting 125 bps between 2024 and 2025 and holding for four consecutive meetings.
- Brent crude above $100 per barrel, elevated geopolitical risk, and a CPI inflation projection of 5.2% for FY27 forced Governor Malhotra's hand on the policy reversal.
- Indian markets sold off immediately — Sensex down 429 points, Nifty down 173 — and the move amplifies a global signal that central bank re-tightening is not confined to the United States.
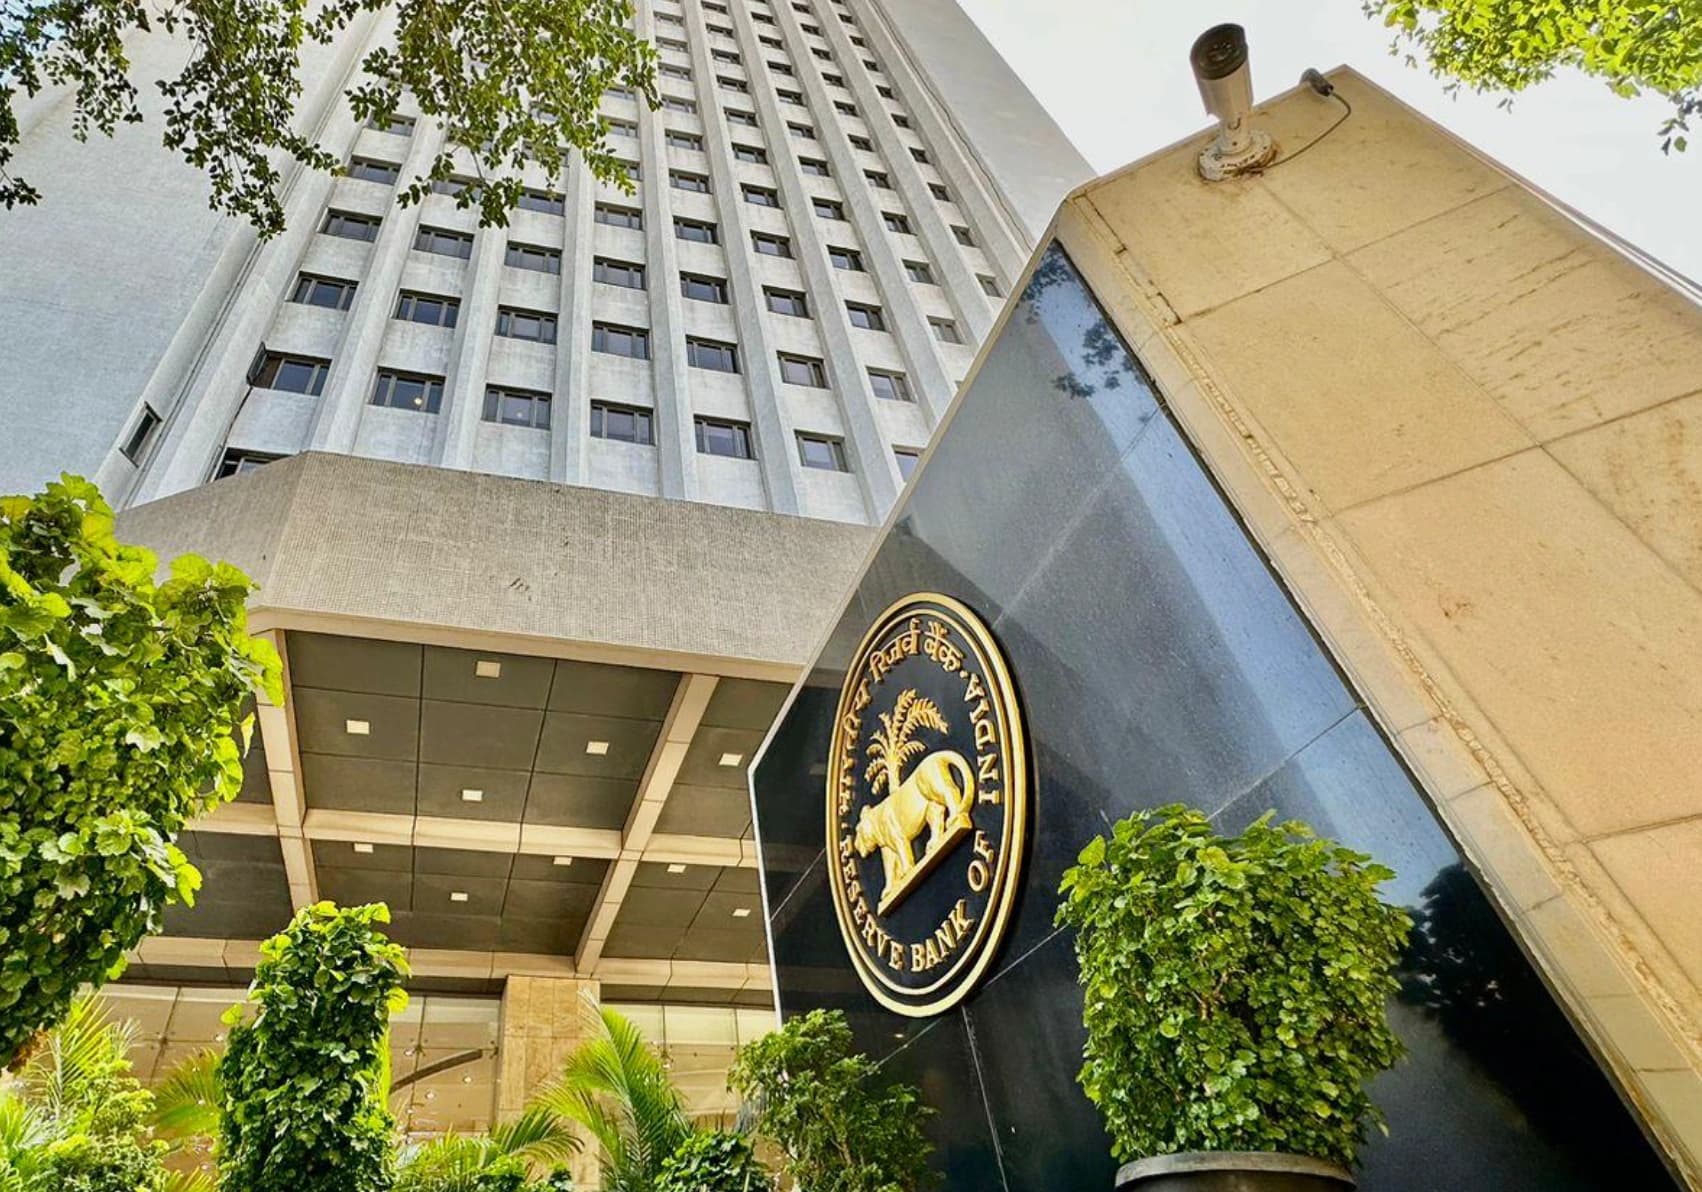
The Reserve Bank of India's monetary policy committee voted unanimously today to raise the repo rate by 25 basis points to 5.50%, ending a 16-month easing cycle that had delivered 125 basis points of cuts and marking the first rate increase from the RBI in nearly four years. The Sensex fell 429 points and the Nifty dropped 173 points in immediate response, as investors processed what is, in effect, a full policy regime change in one of the world's fastest-growing major economies.
A 125 bps Easing Cycle, Fully Abandoned
To understand what happened today, start with the math of the reversal. The RBI cut its repo rate from 6.50% down to 5.25% across 2025 — a 125-basis-point easing cycle designed to stimulate growth and manage global spillover risks. The rate held at 5.25% through four consecutive MPC meetings, suggesting the committee believed it had done enough. Today's 25-basis-point hike to 5.50% signals that the calculus changed — not gradually, but decisively enough to produce a unanimous 6-0 vote on the first move upward since 2022.
Governor Sanjay Malhotra's rationale is straightforward and multi-layered. The RBI revised its FY27 real GDP growth forecast upward to 7.1%, which removes the primary justification for holding rates at stimulative levels. When an economy is growing at 7.1%, accommodative monetary policy is not neutral — it is actively adding fuel to potential inflation. At the same time, the RBI's own FY27 CPI inflation projection sits at 5.2% with risks skewed higher, and core inflation is pegged at 4.4%. Neither number is catastrophic in isolation, but both are well above the RBI's 4% target midpoint, and the directional risk is clearly upward rather than downward.
The single most important external variable in today's decision is Brent crude above $100 per barrel. India imports roughly 85% of its oil needs, which means an elevated crude price is not a terms-of-trade headwind that monetary policy can easily offset — it is a direct, persistent inflationary input that feeds through to fuel, transport, and food prices across the entire supply chain. The RBI explicitly cited Brent crude as a material upside risk to its inflation projections. A central bank that is already projecting CPI at 5.2% and watching oil above $100 has very limited room to maintain an accommodative stance without risking a loss of inflation credibility.
The Global Re-Tightening Signal
The RBI's move does not exist in isolation. Read it alongside the Fed's September hike to 3.75%–4.00%, the Bank of Japan's September move to 1.25%, and the ECB's inflation projection of 3.0% for 2026, and a pattern emerges: after a global easing phase that ran through much of 2024 and into 2025, major and significant emerging-market central banks are tightening again — or signaling that they will.
This matters for cross-asset traders in a specific way. Emerging market economies that had been benefiting from easier domestic financial conditions now face higher borrowing costs at precisely the moment that global risk appetite is being tested by elevated energy prices and geopolitical uncertainty. India's domestic equity market reaction today — Sensex off 429 points, Nifty down 173 — is the most visible example, but the transmission mechanism runs deeper than a single session's price action. Higher repo rates in India mean tighter conditions for Indian corporates that have been refinancing and expanding on the back of cheap credit. It also means Indian government bond yields reprice upward, which competes with equity valuations for domestic institutional capital allocation.
The unanimous nature of the MPC vote is the detail that carries the most forward policy signal. A split vote — say, 4-2 or 5-1 — would have suggested a committee divided between growth preservation and inflation fighting, leaving the door open for a quick reversal if conditions softened. A 6-0 unanimous decision communicates institutional conviction. It tells markets that this is not a one-meeting reaction to a single data point but a deliberate regime shift toward tighter policy. For India-focused traders, that distinction matters enormously for sequencing future MPC meetings and positioning in Indian rate-sensitive sectors.
What Comes Next for India and EM Broadly
The RBI's next scheduled meeting will now arrive with markets asking one question: was 5.50% a one-and-done recalibration, or the start of a tightening cycle? The answer depends almost entirely on three variables. First, Brent crude: if oil retreats meaningfully below $100 — say, toward the $85–$90 range — inflationary pressure from the energy channel eases and the RBI can credibly pause. If crude stays above $100 through November, another 25-basis-point hike becomes the base case. Second, CPI prints: the RBI's own projection of 5.2% for FY27 assumes current conditions persist. Any sequential monthly CPI surprise above that path — particularly in food inflation, which is structurally volatile in India — pulls the next hike decision forward. Third, rupee stability: the rupee's performance against the dollar in coming weeks will influence the RBI's calculus on imported inflation. A weakening rupee amplifies the crude oil inflation channel; a stable or strengthening rupee provides the committee with some breathing room.
For traders with broader emerging-market exposure, today's RBI decision is the clearest confirmation yet that the EM easing trade that defined 2024-2025 positioning is over. The 10-year Indian government bond yield will be the cleanest instrument to watch for the RBI's evolving signal — any move above the 7.50% threshold in coming sessions would indicate the market is pricing a full tightening cycle rather than a single-meeting adjustment. Equity traders in India-facing funds or ETFs should note that Indian banking stocks, which had benefited from the spread compression created by cheap RBI lending, are now repricing in the opposite direction. The Nifty Bank index, which had outperformed the broader Nifty 50 during the easing cycle, is the sector most directly exposed to margin pressure as repo rates rise. The RBI's next decision date is the level and event to mark: the policy regime has changed, and the burden of proof for a pause now falls on the inflation data, not on economic growth.
The Weekly Investor
Daily market analysis for active traders. Free.