Ericsson Surges 11% While Dow Defies the Tech Rout
Ericsson beats Q3 estimates by 29% on EPS as Dow futures add 139 points, signaling sharp defensive rotation away from Nasdaq's chip-driven collapse.
Key Points
- Ericsson reported Q3 EPS of 18 cents versus the 14-cent consensus estimate — a 29% beat — on $6.168 billion in revenue that topped the $5.790 billion estimate, driving shares up 10.9% to $10.74 in premarket trading.
- The Dow Jones Industrial Average is running in stark contrast to the Nasdaq, with Dow futures adding 139 points overnight as investors rotate into industrials, utilities, and telecom names that benefit from infrastructure spending rather than AI capex cycles.
- Ericsson's volume — 1.29 million shares in early trade — confirms institutional conviction, and the stock's next test is whether it can hold above $10.50 through today's close to establish a new technical base.
Ericsson posted Q3 earnings of 18 cents per share Thursday morning against a consensus estimate of 14 cents — a 29% beat that sent shares up 10.9% to as high as $10.74 in premarket trading on volume of 1.29 million shares. In a session where $1 trillion in chip stock value has evaporated, the Swedish telecom equipment maker is running the opposite direction, and it is not alone.
The Number That Changed Ericsson's Morning
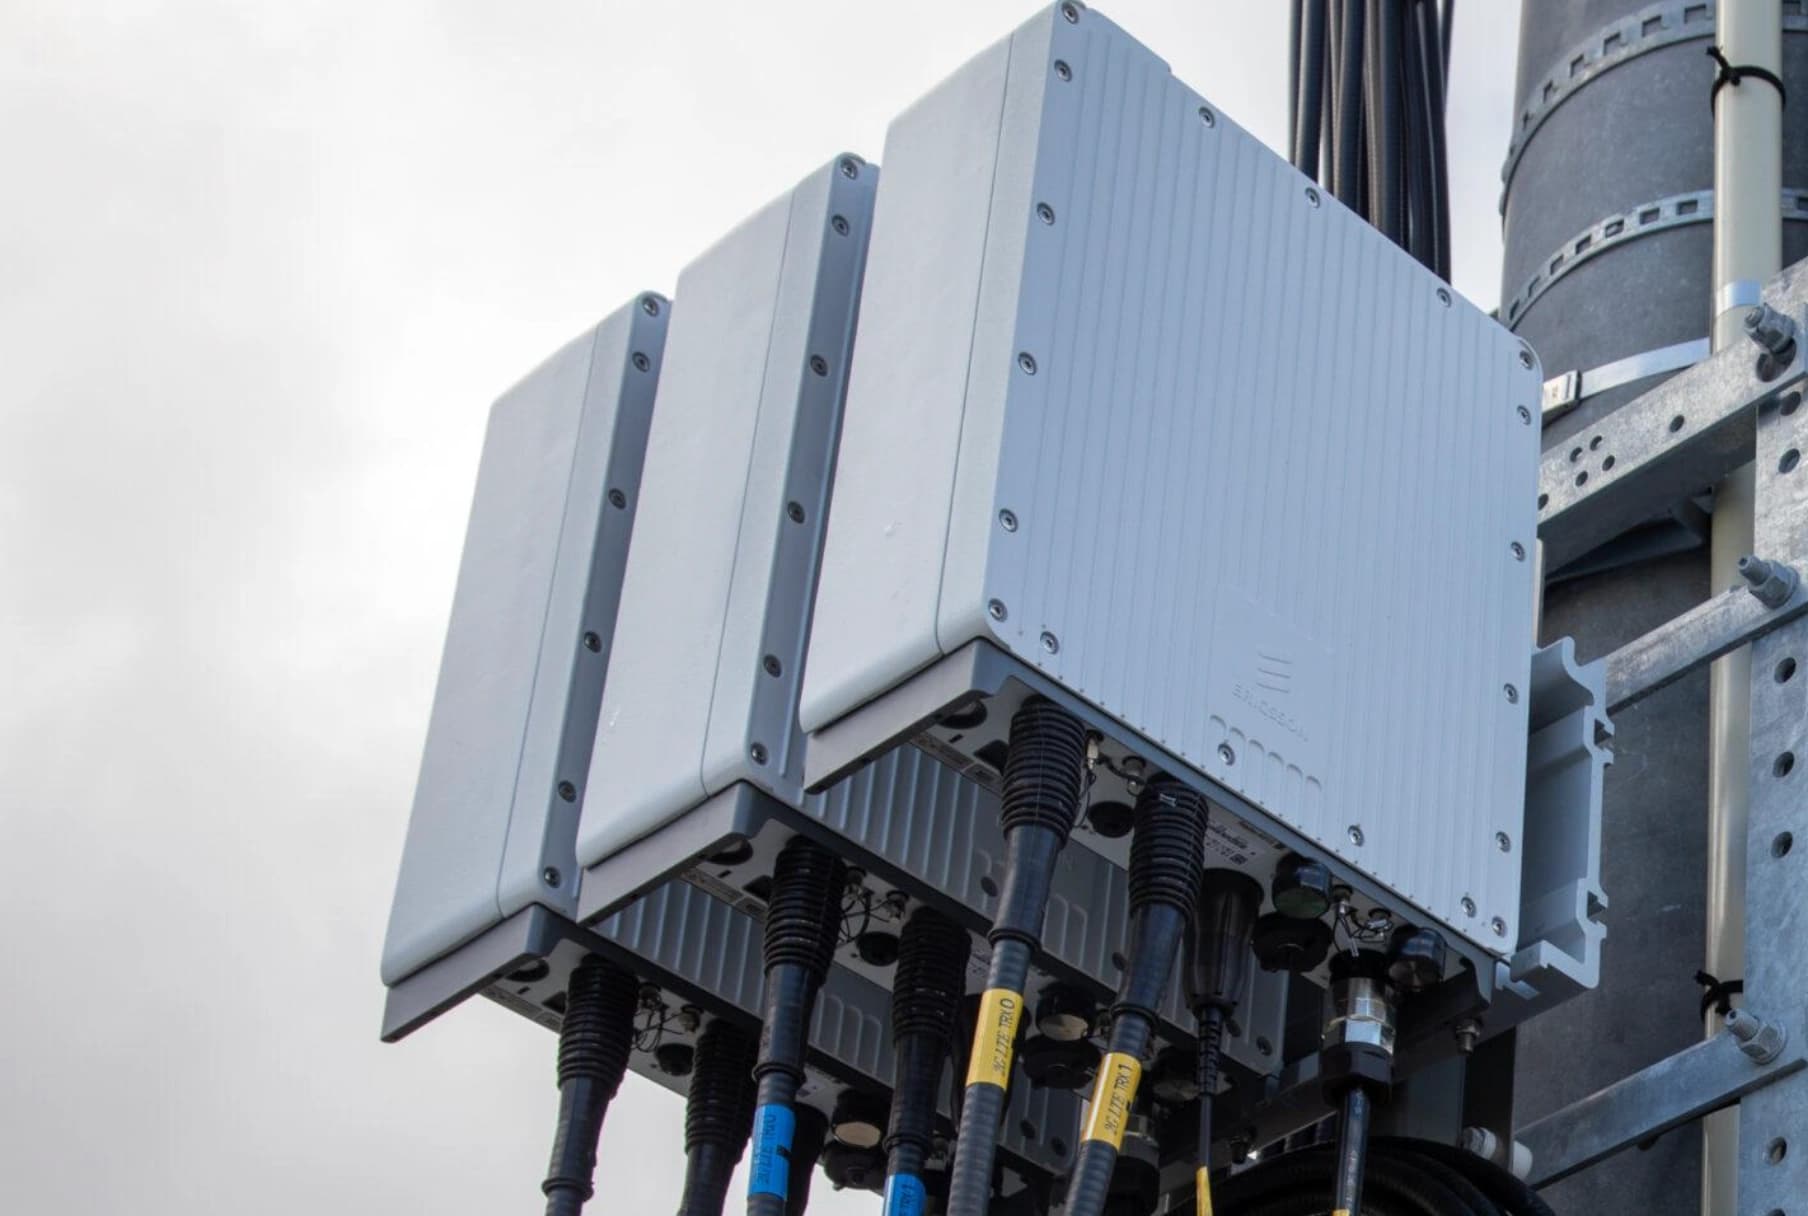
The revenue line was just as clean as the earnings beat. Ericsson reported quarterly sales of $6.168 billion against the $5.790 billion analyst estimate — a $378 million top-line surprise on a base where most telecom equipment companies have been fighting for flat organic growth. The company also reported 7% organic growth, a metric that strips out currency effects and acquisitions and speaks directly to underlying demand for 5G network infrastructure. That number is not a rounding error. In an environment where telecom carriers globally have been throttling capital expenditure on new network builds, 7% organic growth signals that the next phase of 5G densification spending is arriving earlier than the consensus model assumed.
The significance extends beyond Ericsson's own stock. The company's equipment goes into carrier networks across North America, Europe, and emerging markets. When Ericsson beats on organic growth, it is telling the market something real about operator spending intentions — and operator spending intentions are a leading indicator for a different kind of infrastructure cycle than the AI data center buildout that is currently imploding. Carriers are not borrowing at floating rates to buy depreciating GPUs. They are executing multi-year network contracts with predictable cash flows, and Ericsson's results suggest those contracts are accelerating.
The Dow's Divergence Is the Real Market Signal
Dow futures added 139 points overnight, or 0.3%, while Nasdaq-100 futures shed 1.1% and the S&P 500 dropped 0.3%. By mid-session, the Dow December contract was trading near 51,893, off just 0.08% — holding its gains relative to a broad market under pressure. That is not a coincidence or noise. It is sector rotation executing in real time, and the speed of the divergence is notable.
The Dow's composition is the key. The index's 30 components are heavily weighted toward industrials, financials, healthcare, and consumer staples — sectors that either benefit from a higher-rate, higher-inflation environment or are largely insulated from the AI capex cycle's boom-bust dynamics. When CPI prints at 3.6% year-over-year with a 0.6% monthly surge driven by energy, money moves away from long-duration growth assets and toward companies with pricing power and near-term cash generation. That is precisely what Thursday morning's tape is showing.
PPG Industries is up 5.76% to $110.91 in premarket trading — a coatings and specialty materials company whose pricing power in an inflationary environment is straightforward. Nutrien, the Canadian fertilizer giant, added 5.51% to $73.72, benefiting from energy-driven commodity price tailwinds. National Grid rose 4.71% to $82.21 as utility names attract yield-seeking capital rotating out of growth. These are not glamorous trades. They are inflation-regime trades, and they are working on a day when the Nasdaq is getting taken apart.
Reading the Rotation for What Comes Next
The Russell 2000 is the complicating factor in the clean defensive-rotation narrative. Small-cap futures are down 1.34% to 2,762.50 — worse than the S&P 500 and roughly in line with the Nasdaq. Small caps are theoretically "domestic" and "real economy" plays, but they are also disproportionately debt-dependent. A 3.6% CPI print that cements higher-for-longer rates is a direct hit to small-cap balance sheets across industrials, consumer discretionary, and regional banking. The Russell's underperformance today is not a contradiction of the defensive rotation thesis — it is a clarification of it. Investors are not buying "small" or "domestic." They are buying "cash flow positive" and "pricing power." Size is irrelevant. Quality is everything.
Ericsson's 1.29 million shares of premarket volume is the institutional fingerprint on this trade. Retail investors do not drive that kind of premarket liquidity in a mid-cap telecom equipment stock. Fund managers are adding exposure deliberately, not chasing a gap. The stock's 10.9% move on results of this quality is also not a stretched reaction — prior to Thursday, ERIC had been essentially flat on the year, meaning there was no priced-in optimism to fade. The beat is landing on a clean base, which is exactly the setup where earnings gaps tend to hold rather than fill.
The forward question is whether Ericsson's results catalyze a broader re-examination of the telecom equipment sector, which also includes Nokia and CommScope. Nokia reports next week. If Nokia's organic growth numbers corroborate Ericsson's 7% figure, the sector rotation trade has a second leg. For Ericsson specifically, the immediate technical level to watch is $10.50 — that price represents the stock's previous resistance zone from earlier in 2026. A close above that level today on sustained volume would establish a new trading range and shift the intermediate-term chart structure from neutral to bullish. A fade back below $10.00 would suggest the gap was a one-session event driven by the earnings beat rather than the beginning of a durable re-rating. Nokia's earnings release next week, combined with any guidance updates from major U.S. carriers on their own Q3 calls, will determine which outcome is more likely.
The Weekly Investor
Daily market analysis for active traders. Free.