APLD Reports Tonight: $31B Backlog vs. 20.9% Short Float
Applied Digital reports fiscal Q1 2027 after the close today. A $31B backlog and 75 MW activation set up a potential short squeeze — or another EPS miss.
Key Points
- Applied Digital enters its fiscal Q1 2027 print with 20.9% of float sold short and a $31 billion contracted backlog — the squeeze math is real if the company delivers even a modest beat.
- The bull-bear tension is structural: APLD has demonstrated both a 111% EPS beat and a -333% EPS miss in consecutive quarters, making the earnings pattern genuinely unpredictable.
- Watch the revenue line and management commentary on Polaris Forge 1 ramp timing — if activation guidance is pulled forward, that is the catalyst that moves the stock tonight.
Applied Digital drops its fiscal Q1 2027 numbers after the close today at 5 PM ET, and the setup is as binary as any print in AI infrastructure this year. Consensus sits at a loss of $0.30 per share on revenue of $116.3 million — but APLD has obliterated and cratered those estimates in back-to-back quarters with equal conviction, which means the consensus number is almost beside the point.
The Case File on APLD's Earnings History
The most important thing to understand about Applied Digital going into tonight is that the company's earnings record is not noisy — it is structurally unpredictable in a way that requires position discipline on both sides. In its most recent report, APLD posted a loss of $0.39 per share against a consensus estimate of -$0.09, a miss of 333%. Revenue in that same print came in at $258.75 million, beating estimates by 167%. The pattern is not random: APLD is a capital-deployment machine that consistently outgrows its revenue recognition timeline while the cash leaves the building first.
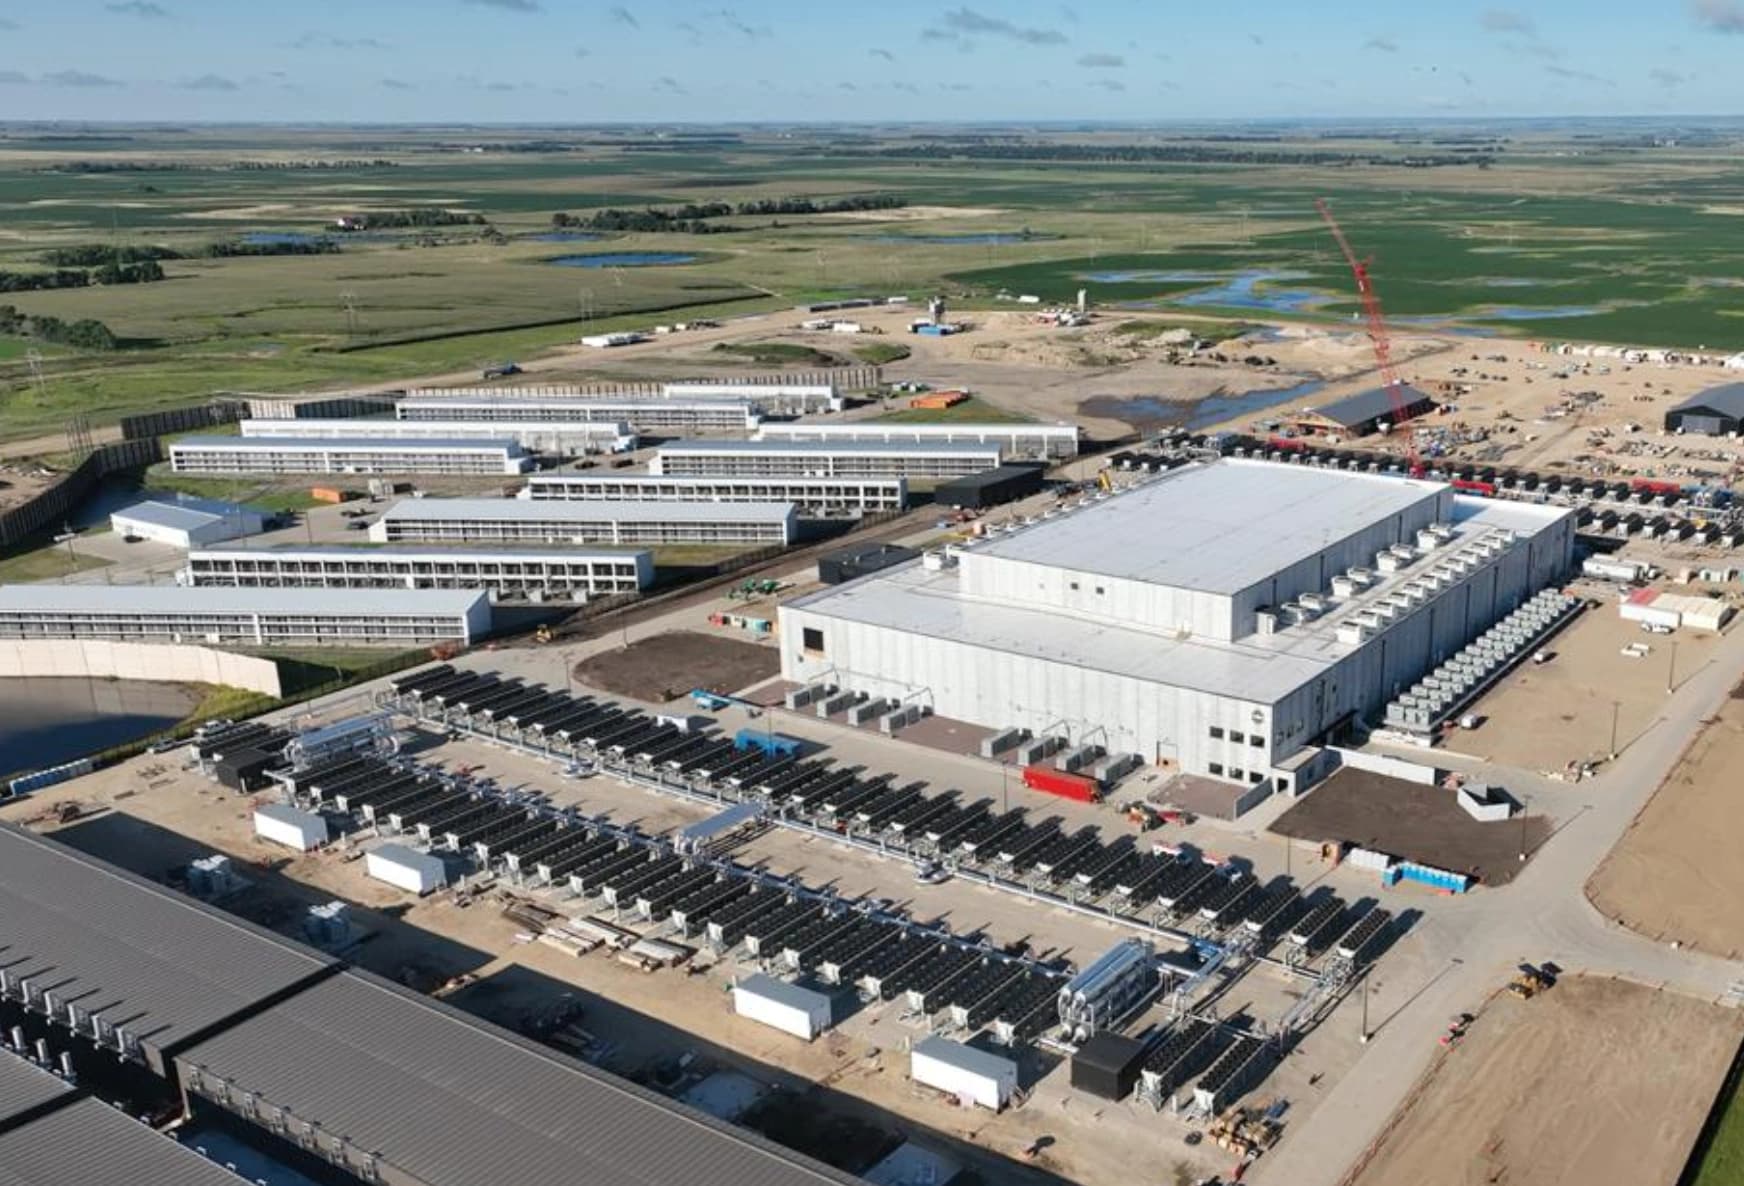
The quarter before that told the opposite story. APLD posted EPS of $0.04 against a consensus of -$0.36, beating by 111%. That is a swing of roughly 450 basis points in earnings surprise between two consecutive reports. For traders, the implication is straightforward: the EPS line is nearly uninvestable as a signal. What matters tonight is the revenue number, the backlog update, and — critically — any language around activation timelines for Polaris Forge 1, the 75 MW facility APLD flagged as a near-term catalyst heading into this print.
The fiscal 2026 capex figure makes the timing problem tangible. APLD spent approximately $3.04 billion in fiscal 2026, with $2.99 billion of that allocated to HPC Hosting infrastructure. That is cash out the door now for revenue that flows in over multi-year contracts. The $31 billion contracted backlog is the long story, and it is a legitimate one — but the gap between cash deployed and cash received is exactly where short sellers are camping, and 20.9% of float sold short is an unusually large position ahead of a binary event.
The Squeeze Setup and Its Limits
Twenty point nine percent short interest is the number that has options desks paying attention today. A meaningful beat — particularly on revenue or in the form of an upward backlog revision — could trigger a mechanical covering event that amplifies any rally far beyond what the fundamental improvement would justify on its own. The Finland AI campus announcement and the Polaris Forge 1 activation are both fresh enough that they have not been fully digested into price, which means management's characterization of execution progress on those projects carries outsized weight tonight.
But the squeeze setup has structural limits that experienced traders should price in. Short sellers in APLD are not purely speculative — they are hedging a real thesis around customer concentration, financing cost escalation, and the gap between backlog and recognized revenue. Rising interest rates in the capital-intensive data center sector are not a theoretical risk for APLD; they are a direct P&L line item given the scale of the company's debt load relative to its current revenue base. The Zacks pre-earnings call framing "fold" as the more logical position than holding is not noise — it reflects a valuation that requires near-perfect execution on a $31 billion backlog that has not yet generated anything close to commensurate revenue.
According to Yahoo Finance's pre-earnings analysis, the core concern heading into tonight is not whether APLD has the contracts — it clearly does — but whether the company can manage its capital structure while those contracts season into cash flow. That is a multiyear question being asked at a moment when the market wants a quarterly answer.
The AI infrastructure theme itself is not in dispute. Hyperscaler capex commitments for 2026 and 2027 remain at historic levels, and companies like APLD that own physical capacity are positioned to benefit from a supply constraint that is measured in years, not quarters. The question tonight is whether APLD's specific execution — particularly around HPC Hosting margin, customer concentration, and the Polaris Forge ramp schedule — can justify a valuation that has already priced in a significant portion of that tailwind.
What Traders Watch After the Close
The binary outcomes here are fairly clean. A revenue beat above $130 million combined with any positive revision to the Polaris Forge 1 timeline creates the mechanical conditions for a short squeeze. The 20.9% short float means that even a modest incremental positive — a backlog number above $31 billion, a customer expansion announcement, or a narrowing of the EPS loss — could cascade into a covering event that drives the stock 10% to 15% higher in the after-hours session before fundamentals reassert themselves at the open.
The bear scenario is equally mechanical. An EPS miss that exceeds the -$0.30 consensus by more than 30 cents, combined with any delay language around Polaris Forge 1 activation or a revision to the Finland campus timeline, removes the near-term catalysts that justify holding through the capital structure risk. In that case, the 20.9% short interest becomes a self-reinforcing pressure, not a squeeze fuel.
The single data point that matters most tonight is not the EPS number — it is the activation megawatt count for Polaris Forge 1 and whether management's language around the Finland campus moves from "plan" to "committed investment with timeline." Those two items are the difference between a story that is building toward its $31 billion backlog and a story that is perpetually one quarter away from inflection. APLD's next major fundamental checkpoint after tonight is its fiscal Q2 2027 report, expected in approximately 90 days — but tonight's print will determine whether the long thesis has earned another quarter of patience or whether the short side gets a fresh catalyst to press.
The Weekly Investor
Daily market analysis for active traders. Free.